How Could Gibran’s Resignation as Vice President Affect Indonesia’s Stock Market?
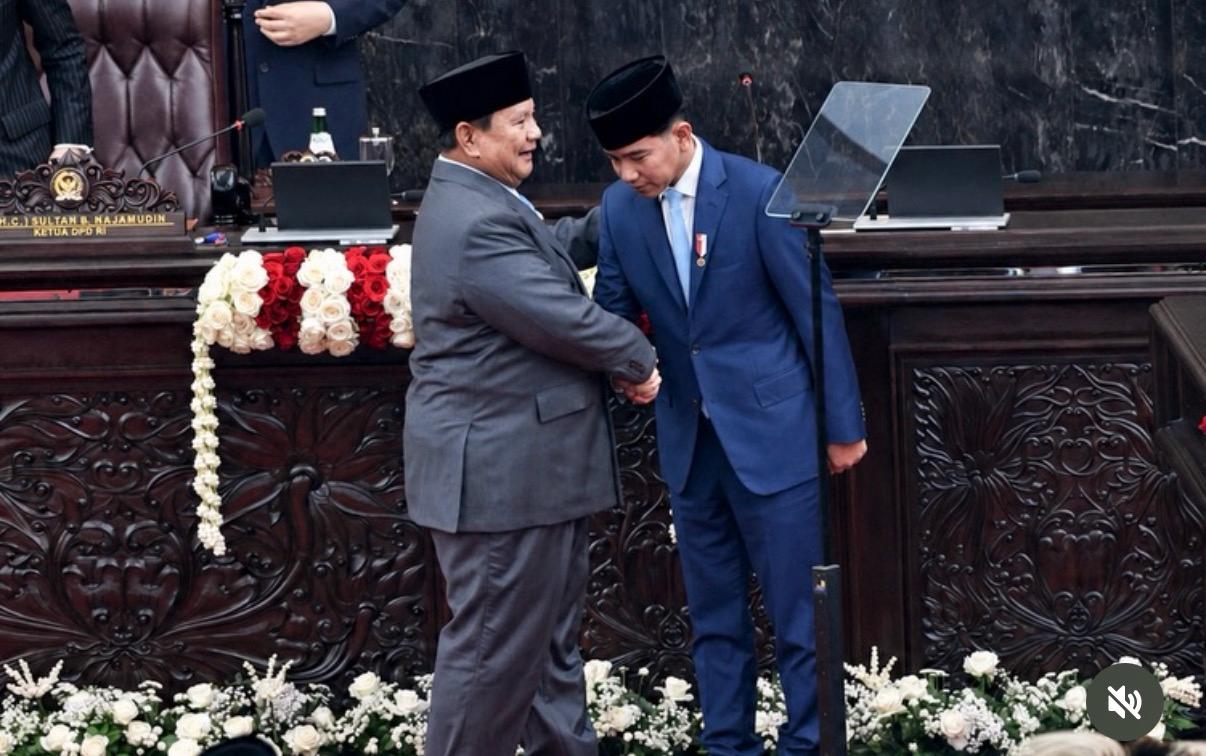
JAKARTA, JakartaWeekly.com—Gibran Rakabuming Raka’s resignation as Vice President could have a positive impact on the stock market in the short term, particularly if the development is perceived as easing political uncertainty and maintaining government stability.
Nafan Aji Gusta, Senior Analyst at Mirae Asset Sekuritas, explained that the capital market is highly sensitive to political uncertainty. When political uncertainty increases, investors tend to adopt a wait-and-see approach, reduce their exposure to risky assets, and even withdraw capital from the market. Conversely, if the political transition proceeds constitutionally and smoothly without disrupting government continuity, it could help restore investor risk appetite.
“Regarding the JCI’s 2.66% gain to 5,250.90 on Thursday, I believe domestic political developments were indeed one of the positive catalysts,” Nafan said.
However, the increase cannot be attributed solely to Gibran’s resignation. Several other factors also contributed, including the market’s response to MSCI’s November review, movements in regional stock markets, and bargain hunting following significant selling pressure in the preceding sessions.
Therefore, the positive impact of this political sentiment is likely to be short-lived. For it to become a sustainable bullish catalyst, the market will still need greater certainty over government policies, improvements in economic fundamentals, and a recovery in foreign investor confidence.
Gibran’s resignation could influence perceptions of Indonesia’s political risk, but the impact will largely depend on how the transition is managed.
Foreign investors do not merely focus on who holds a particular political office. They also consider the quality of institutions, legal certainty, government stability, policy consistency, and the credibility of economic management.
If the process of filling the Vice President’s position proceeds in accordance with the Constitution and does not trigger prolonged political conflict, perceptions of political risk could remain under control.
“However, we also need to recognize that foreign investors are currently facing broader concerns regarding perceptions of investment risk in Indonesia, particularly in terms of capital market transparency, regulatory certainty, corporate governance, and free float policies,” he explained.
In this context, MSCI’s review concerning the possibility of Indonesia being reclassified from an Emerging Market to a Standalone Market remains one of the key challenges in restoring global investor confidence.
Therefore, the government and capital market authorities need to ensure that structural reforms are implemented consistently and transparently, with measurable results. These efforts are essential to restoring the attractiveness of Indonesia’s capital market to foreign investors.
From a sectoral perspective, companies with significant exposure to government strategic projects could be affected if the political configuration changes, particularly if such changes are followed by adjustments to development priorities, budget allocations, or government policy directions.
Several sectors that warrant attention include construction, infrastructure, energy, mining, transportation, as well as companies involved in downstream processing and national strategic projects.
The main risks include potential project reviews, changes in funding schemes, delays in capital expenditure realization, and shifts in government contract allocation priorities.
However, investors also need to distinguish between changes in the political configuration and changes in the fundamental direction of economic policy. Not all strategic projects will automatically be discontinued following changes in the government structure.
If the government maintains its development agenda, including infrastructure development, downstream processing, energy security, and investment expansion, companies with strong fundamentals and long-term contracts may still have opportunities to maintain their business prospects.
Furthermore, several key catalysts warrant investors’ attention through the end of 2026.
First, developments in domestic political stability and government policy continuity. Investors should monitor the process of filling the Vice President’s position and ensure that political dynamics do not disrupt development agendas or the investment climate.
Second, progress in Indonesia’s capital market reforms, particularly regarding share ownership transparency, free float policies, the handling of stocks with high ownership concentration or High Shareholding Concentration (HSC), and further engagement with MSCI. These measures are crucial to restoring confidence among global institutional investors.
Third, rupiah exchange rate stability and Bank Indonesia’s monetary policy. A more stable rupiah could help ease pressure on foreign capital flows while maintaining perceptions of Indonesia’s investment risk.
Fourth, developments in global interest rates, particularly the Federal Reserve’s monetary policy direction and movements in US Treasury yields. These factors will influence global capital allocation to emerging markets, including Indonesia.
Fifth, the realization of domestic economic growth, household consumption, investment, government spending, and corporate earnings performance in the fourth quarter of 2026. Improving corporate fundamentals will be an important foundation for sustaining the JCI’s recovery.
Sixth, movements in global commodity prices, particularly gold, coal, nickel, and crude oil, given that several commodity-based companies make significant contributions to market capitalization and index movements.
“Overall, I believe opportunities for a JCI recovery remain open. However, investors should recognize that market volatility could remain elevated. The sustainability of the index’s gains will largely depend on a combination of political stability, the credibility of capital market reforms, macroeconomic stability, and the return of foreign capital inflows into the domestic stock market,” he concluded.
Discover more