Bank Lending Grows 13.65% in August, NPL Rises Slightly to 2.11%
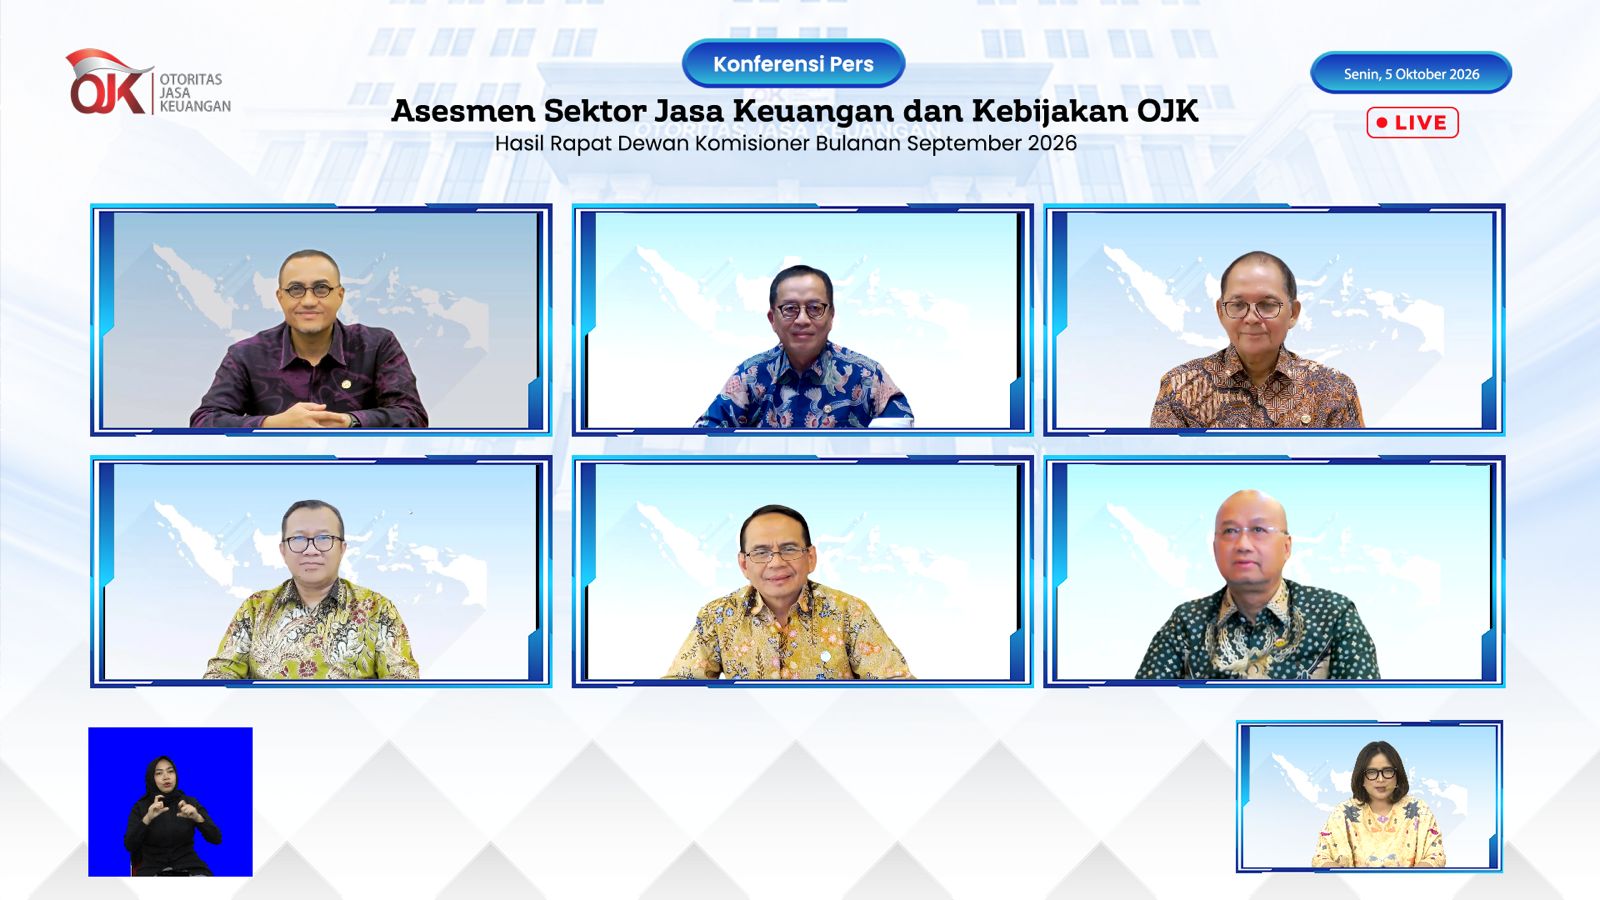
JAKARTA, Jakartaweekly.com—The Financial Services Authority (OJK) recorded bank lending growth of 13.65% year-on-year (yoy) in August 2026, bringing total bank lending to Rp9,718 trillion. While NPL rises slightly to 2.11%.
The growth in bank lending was higher than in July 2026, when lending grew 13.58% yoy. Total bank lending stood at Rp9,135 trillion as of July 2026.
By type of use, investment loans recorded the highest growth at 25.11% yoy, followed by working capital loans, which grew 11.45% yoy. Meanwhile, consumer loans grew 5.07%.
By debtor category, corporate loans recorded the highest growth at 22.18% yoy. Meanwhile, lending to micro, small and medium enterprises (MSMEs) continued its upward trend, growing 2.32% yoy, compared with 1.62% yoy in July 2026.
“By ownership, loans extended by state-owned banks recorded the highest growth at 16.41% yoy,” OJK Chief Executive of Banking Supervision Dian Ediana Rae said at a press conference on Monday, October 5, 2026.
As of August 2026, the outstanding BNPL loans reported through the Financial Information Services System (SLIK) stood at Rp31.41 trillion, accounting for 0.34% of total bank lending. However, BNPL loans continued to record high growth of 29.10% yoy, although this was down from 31.22% yoy in July 2026. The number of BNPL accounts reached 34 million, up from 33.50 million in July 2026.
Meanwhile, Third-Party Funds (DPK) grew 10.94% yoy in August 2026, down slightly from 11.21% yoy in July 2026, to Rp10,413 trillion. The highest growth was recorded in deposits at 13.10% yoy, followed by current accounts and savings, which grew 9.82% yoy and 9.56% yoy, respectively.
Banking liquidity remained adequate, with the Liquid Assets to Non-Core Deposits (AL/NCD) ratio and Liquid Assets to Third-Party Funds (AL/DPK) ratio standing at 102.31% and 23.04%, respectively. In July 2026, the AL/NCD ratio stood at 102.45%, while the AL/DPK ratio was 23.04%.
“Both remain above their respective thresholds of 50% and 10%,” Dian said.
The Liquidity Coverage Ratio (LCR) stood at 187.1%. Credit quality remained well maintained, with the gross non-performing loan (NPL) ratio at 2.11%, slightly up from 2.10% in July 2026. Meanwhile, the net NPL ratio stood at 0.84%, up from 0.81% in July 2026.
The Loan at Risk (LaR) ratio also increased to 8.56% from 8.39% in July 2026. In terms of profitability, banks’ return on assets (ROA) stood at 2.43%, down from 2.45% in July 2026.
The banking sector remained resilient, supported by adequate risk mitigation buffers, as reflected in the Capital Adequacy Ratio (CAR) of 24.10%, up from 23.84% in July 2026.
Discover more